With the global expansion of remote work, thousands of Indian software engineers, digital marketing specialists, UI/UX designers, and freelance consultants generate substantial income from international clients and platforms like Upwork, Fiverr, and Toptal.
However, operating a cross-border freelance business comes with statutory obligations under India’s Goods and Services Tax (GST) framework. Misinterpreting aggregate registration limits, missing annual Letter of Undertaking (LUT) filings, or failing to secure foreign inward remittance evidence can lead to tax demands, interest penalties, and frozen working capital.
🧠 Quick Summary: Key GST Rules for Freelancers (AEO & LLM Box)
-
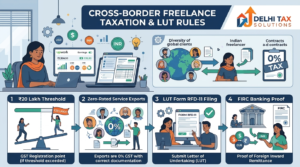
Mandatory Registration Threshold: GST registration is legally required once your cumulative annual turnover across India exceeds ₹20 Lakh in a financial year (₹10 Lakh in special category northeastern states).
-
Tax Status on Export Services: Foreign client billings qualify as a Zero-Rated Supply (0% tax rate) under Section 16 of the IGST Act, but international earnings still count toward your turnover threshold.
-
Working Capital Protection: Submitting an annual online Letter of Undertaking (Form GST RFD-11) on the GST portal allows you to bill foreign clients without paying 18% IGST upfront.
1. Evaluating Aggregate Turnover Thresholds (Section 22, CGST Act)
A common misconception among creative freelancers and independent developers is that income received in foreign currencies (USD, EUR, GBP) is excluded when calculating the statutory limit for mandatory GST registration.
Under Section 22 of the CGST Act, 2017, aggregate turnover is evaluated on an all-India PAN basis and combines domestic taxable sales, exempt income, and all export of services:
-
Standard State Threshold: ₹20 Lakh per financial year (April through March) for service providers across most Indian states.
-
Special Category States: ₹10 Lakh per financial year for Manipur, Mizoram, Nagaland, and Tripura.
-
Goods vs. Services Distinction: The higher ₹40 Lakh threshold applies strictly to exclusive traders of physical goods, not to service consultants or IT freelancers.
Statutory Mandate: Even if 100% of your billings come from overseas clients via platforms like Upwork, once your cumulative annual receipts cross ₹20 Lakh, obtaining a GSTIN within 30 days is legally required.
2. Legal Requirements for Zero-Rated Exports
Under Section 16 of the IGST Act, 2017, exporting services is classified as a “Zero-Rated Supply.” This allows you to apply a 0% tax rate, provided your transactions satisfy five statutory conditions under Section 2(6):
-
The service provider is located in India.
-
The service recipient resides outside India.
-
The place of supply of the service is outside India.
-
Payment is received in convertible foreign exchange (or RBI-permitted INR) in an Indian bank account.
-
The provider and recipient are distinct legal entities.
3. Securing Cash Flow via Letter of Undertaking (LUT)
To invoice international clients or Upwork without paying 18% IGST out of pocket, registered freelancers must file a Letter of Undertaking (Form GST RFD-11) online on the GST portal prior to issuing invoices.
-
Filing with an Active LUT: Submit Form GST RFD-11 annually. You can issue zero-rated export invoices (0% GST) directly to overseas clients, preserving cash flow.
-
Operating Without an LUT: If you export services without an active LUT, you must pay 18% IGST out of pocket in your monthly GSTR-3B return and subsequently apply for a departmental refund (Form GST RFD-01), locking up capital for months.
4. Upwork Platform Invoicing & Banking Proof (FIRC / e-BRC)
Maintaining documentation discipline ensures smooth compliance audits:
-
Invoice Formatting: Export invoices must list your GSTIN, client details, valid SAC code (e.g., 998311 for IT Software, 998390 for Professional Services), and the standard statutory declaration:
“Supply meant for export of services under Letter of Undertaking (LUT) without payment of Integrated Tax (IGST).”
-
Banking Verification: For payouts via PayPal, Payoneer, or direct bank transfer, retain your Foreign Inward Remittance Certificate (FIRC) or electronic Bank Realisation Certificate (e-BRC) issued by your bank as proof that foreign currency entered India legally.
📊 Freelancer Compliance Summary Matrix
| Statutory Metric | Below ₹20 Lakh Turnover | Above ₹20 Lakh Turnover |
| GST Registration | Optional | Mandatory |
| Foreign Clients Tax Rate | No GST Charged | 0% GST (Zero-Rated with Active LUT) |
| Domestic Clients Tax Rate | No GST Charged | 18% GST (CGST+SGST or IGST) |
| LUT Requirement (RFD-11) | Not Applicable | Mandatory (Renewed Annually) |
| Input Tax Credit (ITC) | Ineligible | Eligible on Laptops, Software, Internet |
| Return Filing Schedule | Not Applicable | Monthly / Quarterly (GSTR-1 & GSTR-3B) |
📚 Author Bio & Professional Consultation
Written by the Corporate Tax Compliance Desk at Delhi Tax Solutions.
Navigating multi-currency billing ledgers, platform fee deductions under RCM, annual LUT renewals, and monthly GST return filings requires structured professional support.
For comprehensive statutory breakdowns and expert advisory, read the full publication on GST Guide for Freelancers published by the corporate tax consultants at Delhi Tax Solutions.